AUDITEDTRADER / STATEMENT RECONSTRUCTION
Trading Statement Reconstruction Practice Packet
Six complete invented monetary rows, a twenty-nine-event register and an explicit missing document interval.
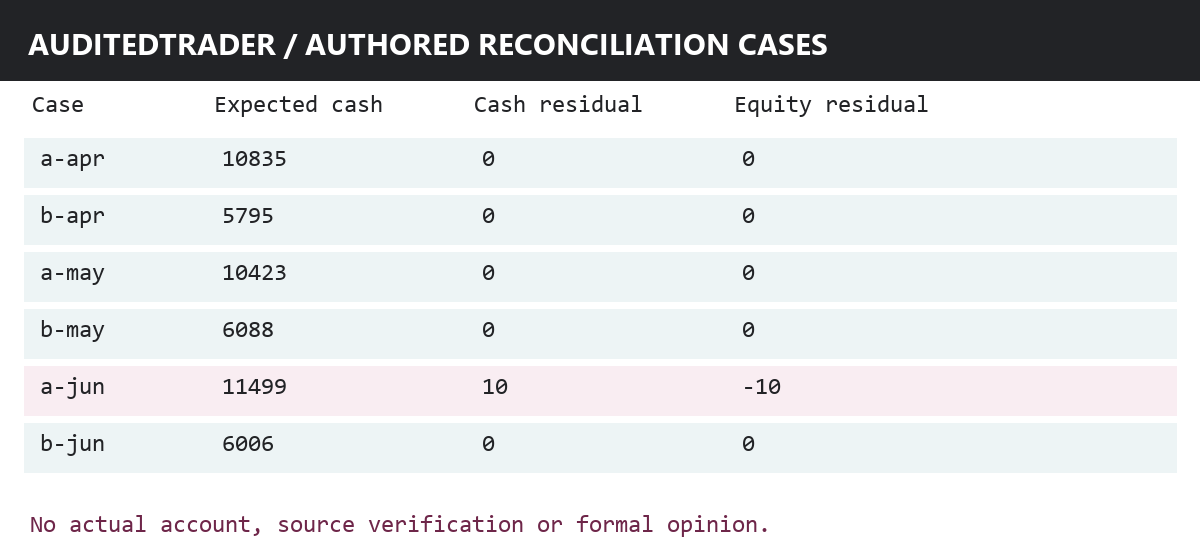
| Case | Expected cash | Reported cash | Cash residual | Equity residual |
|---|---|---|---|---|
| a-apr | 10835 | 10835 | 0 | 0 |
| b-apr | 5795 | 5795 | 0 | 0 |
| a-may | 10423 | 10423 | 0 | 0 |
| b-may | 6088 | 6088 | 0 | 0 |
| a-jun | 11499 | 11509 | 10 | -10 |
| b-jun | 6006 | 6006 | 0 | 0 |
Six calculation rows and their actual teaching scope
The packet contains two invented accounts over April, May and June. Every row includes all twelve monetary inputs, the exact expected outputs and explicit absent real-statement and fill fields. Its twenty-nine movement events are a complete register of the nonzero categories used by those rows. The exercise does not provide intramonth valuations or actual execution dates, so it does not support a time-weighted account return, drawdown or trade win rate.
April: pair the internal movement
Account A begins with ten thousand units and Account B with five thousand. A transfers one thousand to B under a common teaching reference. A also has a two-thousand deposit, five-hundred withdrawal, three-hundred-fifty realised gain, ten income, twenty fees and five financing. Its expected balance is ten thousand eight hundred thirty-five. B's expected balance is five thousand seven hundred ninety-five. The paired transfer cancels only within this declared same-currency invented population.
May: arithmetic agreement cannot supply a missing statement
The May inputs produce exact balances under their declared identities. The document-label manifest nevertheless marks B's May interval missing. Those invented input values therefore do not establish that an original source document exists. A calendar map for B covers April and June but leaves the thirty-one May days uncovered. The row's financial source status cannot be repaired by presenting its arithmetic as independently verified.
June: preserve two distinct discrepancies
A's expected closing balance is eleven thousand four hundred ninety-nine, while the entered reported balance is eleven thousand five hundred nine. Cash residual is plus ten. Its reported equity is eleven thousand four hundred ninety-nine with zero entered unrealised profit; the equity identity using reported balance therefore has a minus-ten residual. The exercise retains both differences. No invented fee, trade or transfer is inserted to make them disappear.
Balance and equity use different observations
The expected cash identity uses opening balance and movement categories. The equity identity uses reported closing balance plus supplied unrealised profit. That choice makes an inconsistent reported cash/equity pair visible instead of silently using an expected amount as a substitute. It does not authenticate either reported value. The full inputs and conventions are available in the JSON and CSV, not just a screenshot of the result.
A complete packet is not complete evidence
The packet is complete as an authored teaching artifact: all six input rows, expected results, twenty-nine movements, six document labels and byte fixtures are provided. It intentionally contains a missing documentary label and an unresolved monetary difference. Completeness of the download is not completeness of real financial evidence. Actual statements, actual fills, strategy validation and assurance opinions remain null.
Inspect the byte identity separately
The two short text fixtures can be hashed in the retained local workbench and compared with their independently prepared SHA-256 digests. A changed byte sequence has its own version and digest. Neither file is a broker statement or an OpenTimestamps proof. This integrity check supplies no historical timing, provenance or investment conclusion.
Permitted conclusion for the exercise
Several supplied monetary identities agree; one has explicit residuals, and the declared B document coverage is incomplete. That is the exercise's conclusion. It is not a clean audit opinion, a person-level rating or a tested product outcome. A real handoff would request original statements, source mapping, timing and reviewer scope before making a broader claim.